Our Financial Services Branding Services

Brand Strategy

Positioning that survives a compliance review and still says something. In this category the constraint usually produces the sharper answer.

Brand Naming

Names that survive Texas Medical Board scrutiny and don’t box you into a single service line as you grow. Austin practices scale fast; names that describe one procedure age badly.

Logo Design & Identity Systems

Identity built to coexist with required regulatory marks — the FDIC official sign, NCUA signage, carrier and network marks — rather than fighting them for space.

Brand Messaging

Claims architecture built for what you’re actually allowed to say, whether that’s SEC marketing rules, FINRA communication standards or deposit insurance accuracy requirements.

Brand Package Design

Branch and office environments, signage systems, print, statements and disclosures, applied consistently across every regulated touchpoint.

Merger & Rebranding

The highest-stakes brand work in this sector. Consolidation is constant, and a botched post-merger rebrand costs deposits, policies and people.

Request A Proposal
Grow Your Finance
Brand With Digital Silk

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
OUR CLIENTS

Trusted Branding Agency for Finance

As a full-service agency, we design and develop branding solutions for businesses of all shapes and sizes.
IBM's logo
IBM
Northwestern University's logo
Northwestern University
Paul Stuart's logo
Paul Stuart
Rollink's logo
Rollink
Spar & Bernstein's logo
Spar & Bernstein
ZipTie transparent logo
ZipTie
Babies R Us logo
Babies R Us
Xerox's logo
Xerox
Absolute Dogs logo and brand identity showcase for pet training platform
Absolute Dogs
Mitsui Plastics's logo
Mitsui Plastics
Puma Energy's Logo
Puma Energy
Enchant Christmas's logo
Enchant Christmas
Grenco Science's logo
Grenco Science

BrandingInside The Rules

  • 01
    Two Regulators Are Moving In Opposite Directions Right Now
    Financial branding has a compliance calendar, and two significant items are live. 

    The FDIC has tightened. The amended Part 328 rule on official signs and advertising took effect on 2 March 2026, with compliance required by 1 April 2027. It requires insured banks to display the FDIC official digital sign on the homepage, on login pages, and on the first page where a customer begins opening a deposit account. It sets constraints on the sign’s color — navy blue, black, or white where legibility requires — and on typography, using Source Sans Pro Web or a similar face. Pages primarily devoted to non-deposit products need their own clear, continuous and conspicuous signage. Sending a customer to a third-party platform for non-deposit products triggers a one-time notification. 

    The final rule is less prescriptive than the original proposal — the fixed hexadecimal codes and mandated font sizes are gone — but the substance stands. For any insured bank, this is a brand system change with a fixed deadline: a required mark, in specified colors, on specified screens, that has to sit alongside an existing identity without looking like an apology. 

    The NCUA has proposed the opposite. In a rulemaking published in December 2025, with comments closing in February 2026, the NCUA proposed eliminating §740.5 — the requirement that federally insured credit unions carry an official advertising statement such as “Federally insured by NCUA.” The official sign requirement under §740.4 would remain; the advertising line would become voluntary. 

    If it’s finalized, credit unions face a question that is purely strategic. You would be permitted to drop a line that has anchored your advertising for decades. Should you? For most, insured status is a trust asset worth keeping voluntarily — particularly for institutions competing against banks whose customers assume insurance without thinking about it. But it becomes a brand decision rather than a compliance default, and it should be made deliberately rather than by whoever updates the template first. 

    Two regulators, eighteen months, opposite directions. Both are brand system events, and both land on people who are usually the last to hear about them. 
  • 02
    Two Regulators Are Moving In Opposite Directions Right Now
    Beyond signage, the language a financial brand can use is constrained in ways that shape positioning directly. 

    Investment advisers operate under the SEC’s marketing rule, which permits testimonials and endorsements but requires disclosure of whether the promoter is a client, whether they are compensated, and any material conflicts — with written agreements for compensated promoters and specific criteria for third-party ratings. Gross performance can’t be shown without net. Hypothetical performance needs safeguards. 

    Broker-dealers work under FINRA’s communication standards. Insured institutions can’t advertise deposit insurance in a misleading way. And across all of it, prohibitions on unfair, deceptive or abusive practices reach marketing claims that a brand team might consider ordinary enthusiasm. 

    The practical consequence is that superlatives and vague trust language are both risky and weak. What works is specific and substantiated — which is better positioning regardless. We build claims architecture from that constraint rather than around it. 
  • 03
    Where Our Financial Work Actually Is
    We are not going to claim depth we don’t have. Our financial services branding sits in three places, and they’re related. 

    Insurance and insurtech. Clear Blue Insurance Group, Xceedance and Zywave are all insurance-sector brands — a carrier, a services and technology partner, and a software platform. Insurance branding has a specific difficulty: nobody wants to think about your category. The brand’s job isn’t affinity, it’s legibility and confidence at a moment that is either obligatory or stressful. And on the B2B side — selling to carriers, brokers and MGAs — the buyer is professionally risk-averse, the cycle is long, and the brand’s job is to make a serious institution feel like a safe choice without feeling inert. 

    Member-owned institutions. Bethpage Federal Credit Union is a credit union, and credit unions have a structural story most of them under-use. Member-owned, not-for-profit, returning surplus to members rather than shareholders — it is a genuine differentiator that a bank structurally cannot claim, and it is routinely reduced to a line on an About page. Field of membership, community charter, the reason the institution exists: these are brand assets. 

    Financial technology serving both. Zywave and Xceedance sit where software meets a regulated industry, which is its own positioning problem — credible enough for a compliance officer, modern enough for the people who will actually use the product. 
  • 04
    Consolidation Makes Rebranding The Defining Engagement
    Banking, insurance and credit unions consolidate continuously. Which means in this sector the most consequential brand work is frequently not a refresh — it’s a merger. 

    Post-merger rebrands are unusually hard here because the stakes are concrete. Depositors and policyholders can leave. Staff at the acquired institution read every brand decision as a signal about whose culture won. Regulators need to see continuity of disclosure. Signage, statements, cards, and every regulated touchpoint have to change on a coordinated schedule. 

    The decisions — retain both names, adopt one, create a third, endorse and phase — are strategic and they are made too fast, usually by people managing an integration rather than a brand. Getting a point of view in early is worth more than any amount of polish later. 
  • 05
    Challengers And Incumbents Have Opposite Briefs
    In most categories, brand maturity runs in one direction. In financial services it inverts. 

    A fintech challenger’s hardest job is signaling safety — that deposits are insured, that the company will exist in ten years, that “move fast” is not the operating philosophy applied to your money. A century-old institution’s hardest job is the reverse: signaling that it is modern, that the app works, that it isn’t a relic.
     
    The same visual and verbal moves that solve one problem cause the other. Knowing which brief you’re actually working on is most of the strategy, and a surprising number of financial rebrands get it backwards — legacy institutions chasing startup aesthetics while startups reach for pillars and serif type. 

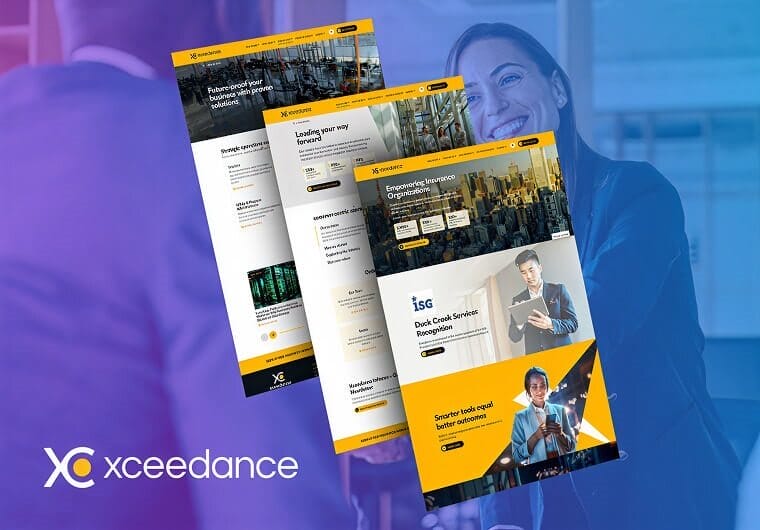
Xceedance – Twenty years of expertise, with an identity that shows it

Xceedance serves insurance clients with fast, fully automated technology, though its old site did little to signal that market leadership, to clients or prospective talent.

We delivered a conversion-optimized site with consistent branding, with a top-of-funnel campaign page, custom modules, Salesforce integration and an employer-branded careers page.

The site drew more than 200,000 new users in six months.

Xceedance website design featuring modern digital layouts that showcase insurance technology solutions, operational support services, and data-driven business capabilities.

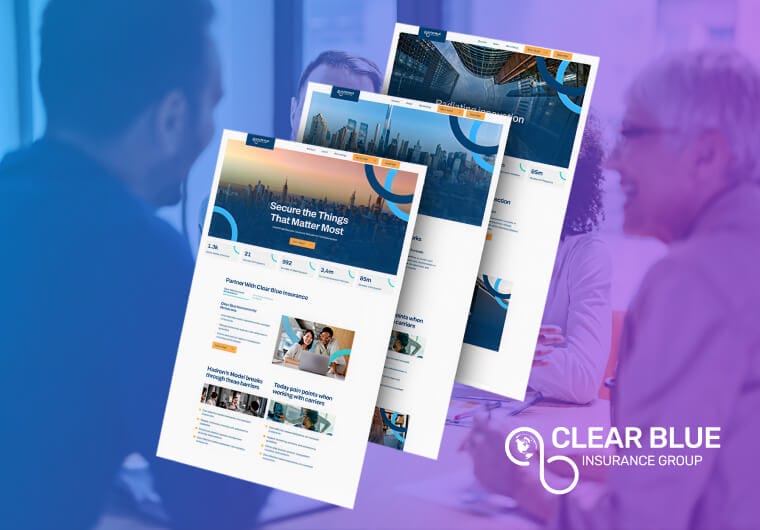
Clear Blue Insurance Group – A full rebrand, for a trusted insurance name

Clear Blue Insurance Group is a trusted provider of solutions for carriers and managing general agents.

Our experts led a full rebrand, with a clear strategy, refreshed logo, color system and brand book, then a custom site with unified messaging.

Authority and trust now come through at a glance, across every channel and partner.

Three stacked images of Clear Blue Insurance Group's website design

What Financial Brands Get Wrong

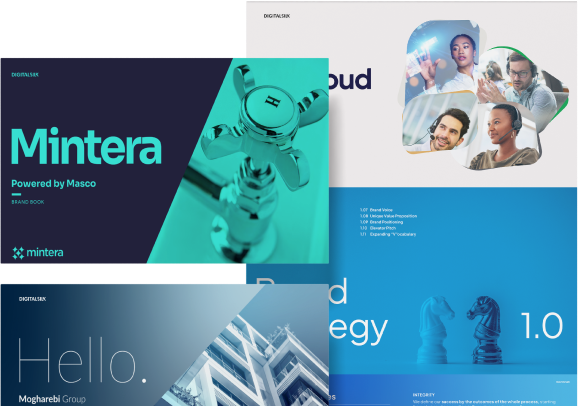
A collage of brand books and promotional materials

“TRUSTED” ISN’T POSITIONING

Every competitor claims it, which makes it worthless as differentiation. Trust is the outcome of specificity — what you do, for whom, better than whom — not a word you put in a tagline.
Financial services web design background

THE REQUIRED MARKS ARE AN AFTERTHOUGHT

The FDIC sign, NCUA signage and carrier marks get bolted on at the end, where they look like compliance clutter. Designed in from the start, they read as credentials.
Diverse group of business professionals engaged in a collaborative meeting, discussing ideas and strategies around a conference table in a modern office setting.

THE BRIEF IS INVERTED

Legacy institutions chase startup aesthetics while challengers reach for gravitas. Both are solving the other’s problem.
Man presenting marketing strategies on board

THE MERGER ARRIVES WITHOUT A BRAND PLAN

Consolidation is constant in this sector, and the naming and architecture decisions get made in an integration meeting under time pressure. That’s where the value leaks.

Our Finance Branding Process

As a financial services branding agency, we’ve built a simplified step-by-step process that we customize for every project.
  • 01
    Discovery

    We start with a discovery call, digging into your objectives, needs, desired position and value proposition as a financial institution.

    We also review your messaging against Regulation Z advertising requirements and UDAAP standards at this stage, along with any marks your institution must carry, such as Member FDIC or Equal Housing Lender. Building the brand platform inside those constraints from day one means we won’t need to edit it back into shape later.

  • 02
    Strategy

    After the discovery call, we conduct extensive market research into trends, best practices and client behavior across the financial services space.

    As a dedicated finance branding team, we analyze that research for gaps and opportunities, identifying where your institution can stand apart from competitors instead of blending in with them.

  • 03
    Brand Book & Guidelines

    Next, our designers produce a comprehensive brand book and style guidelines, giving you a clear roadmap for the brand you’re building.

    We document everything from tone of voice to visual application here, so you can maintain consistency across every touchpoint as your institution grows into new markets.

  • 05
    Rollout

    Finally, we map out a rollout plan across every regulated touchpoint, branch signage, account statements, required disclosures, cards and digital properties, so nothing launches out of sequence or out of compliance.

    We sequence that plan against any compliance deadline already in play, whether that’s a merger, a charter conversion or a regulator-driven timeline, so your rebrand lands on schedule instead of racing a deadline at the end.

Why Financial BrandsWork With Digital Silk

  • 01
    Regulated-Industry Fluency
    We build claims architecture for categories where what you can say is constrained, and treat the constraint as a route to sharper positioning
  • 02
    Insurance And Member-Owned Depth
    Carriers, insurtech platforms, insurance services and credit unions. Real work in the parts of finance where the brand problem is hardest to articulate.
  • 03
    Project Ownership
    One team from research through rollout. Strategy and execution don’t get split between vendors.
  • 04
    Measured Growth
    Brand architecture designed to absorb an acquisition, because in this sector one is usually coming.

Financial Services Branding FAQs

How does the new FDIC signage rule affect our brand?

The amended Part 328 rule took effect on 2 March 2026 with compliance required by 1 April 2027.

It requires the FDIC official digital sign on your homepage, login pages and the first screen of deposit account opening, with constraints on color and typography, plus separate signage for pages about non-deposit products.

Practically, it’s a brand system change — a required mark that has to live alongside your identity on your most valuable screens. Handled well it reads as a credential; handled late it reads as clutter.

If the NCUA drops the advertising statement requirement, should we stop using it?

Probably not, but it becomes your decision rather than a rule. The NCUA proposed eliminating §740.5 in December 2025; the official sign requirement under §740.4 would remain.

For most credit unions, insured status is a trust asset worth keeping voluntarily — especially against banks whose customers assume insurance without thinking. What changes is that you can now place it deliberately, where it does work, instead of everywhere by default.

What can we say about performance and results?

It depends on your registration. Investment advisers operate under the SEC marketing rule — testimonials and endorsements are permitted with disclosure of client status, compensation and conflicts, and gross performance can’t be presented without net. Broker-dealers work under FINRA’s standards.

Insured institutions can’t advertise deposit insurance misleadingly. We resolve this during strategy, because it determines which proof points the brand can be built on.

We’re merging. When should branding start?

Earlier than most institutions think — ideally while the naming and architecture decision is still open, not after it’s been made in an integration meeting.

The choice between retaining both names, adopting one, creating a new one or endorsing and phasing has consequences for depositors, policyholders and staff retention, and it’s very expensive to revisit.

We’re a fintech. How do we signal we’re safe without looking dated?

By being specific rather than borrowing the visual language of incumbents. Serif type and columns don’t create trust; concrete answers do — who holds the deposits, who insures them, who regulates you, who’s behind the company. The brands that solve this well look modern and say serious things, rather than looking old to seem serious.

Do you do the website too?

Yes. Brand strategy and identity usually run first, since the site is one expression of the system rather than the system itself.

Do you work with commercial banks and wealth managers?

Our deepest financial work is in insurance, insurtech and member-owned institutions. The strategic problems — regulated claims, trust as a generic category promise, consolidation — carry across the sector, and we’re happy to talk about fit honestly rather than claim depth we haven’t earned.

Meet With Our Financial Services Branding Team

Tell us what’s driving the timing — a merger, a compliance deadline, a competitor that suddenly looks better than you. We’ll come back with a straight read on whether this is a positioning problem, an identity problem, or a sequencing problem. 
Take The Smart Road To

Digitizing Your Business Growth

Follow Us

Start A Conversation With Us

"*" indicates required fields
This field is for validation purposes and should be left unchanged.